Domestic funds drive India’s $3.5 billion private credit market

India’s private credit market held steady in the first half of 2026, with $3.5 billion invested across 102 deals, according to EY. Domestic funds accounted for almost three-quarters of that value, a sign, the firm says, of a maturing local market.
The headline number barely moved; almost everything behind it did. A year ago, two out of every three private credit dollars deployed in India came from abroad – now three out of four come from home, according to the half-yearly update from EY’s debt and special situations practice.
Deployment held up against a volatile global backdrop of geopolitical tension and commodity price swings, supported by a domestic credit ecosystem in which bank credit grew 18% year-on-year and NBFC credit 16.6%. Beneath the flat total, however, the report describes a market changing shape rather than size.
A steady total, a busier market
The $3.5 billion invested in the first half was broadly in line with the $3.4 billion of H2 2025, but spread across more transactions: 102 deals above $10 million, up from 87. Mid-market tickets of $10 million to $60 million made up 87% of deal count and 61% of deal value, while deals above $120 million fell to 18% of value, from 27% six months earlier.
The comparison with a year earlier is less flattering. H1 2025 saw $9.0 billion deployed, though that figure was inflated by a single transaction – the $3.1 billion refinancing of the Shapoorji Group. EY also notes its tally understates the market, as it excludes deals under $10 million, venture debt, financing of financial services borrowers, NBFC term loans, and offshore raises.
Domestic funds take the lead
The clearest shift is in who supplies the capital. Domestic funds accounted for 74% of deal value and around 79% of deal count in H1 2026. The share of global funds in deal value has slid from 68% in H1 2025 to 36% in H2 2025 and now 26%.
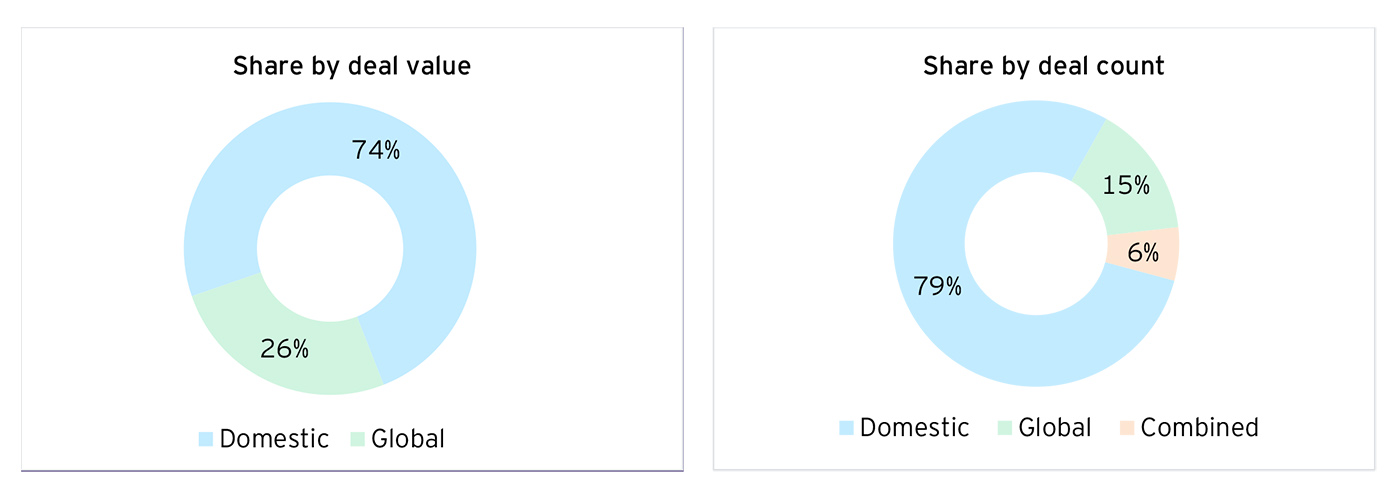
EY attributes the swing to the local presence of Indian funds and their access to mid-market borrowers. Unlike in earlier periods, domestic players were also active in relatively larger transactions during the half – a sign they are no longer confined to the lower end of the ticket range.
Real estate leads, food and beverage arrives
Real estate remained the busiest sector, at 35% of deal value, down from around 42% in H2 2025, followed by healthcare at 13%. The newcomer is food and beverage: at 12%, it emerged as the third-largest sector by deal value, up from roughly 1% six months earlier.
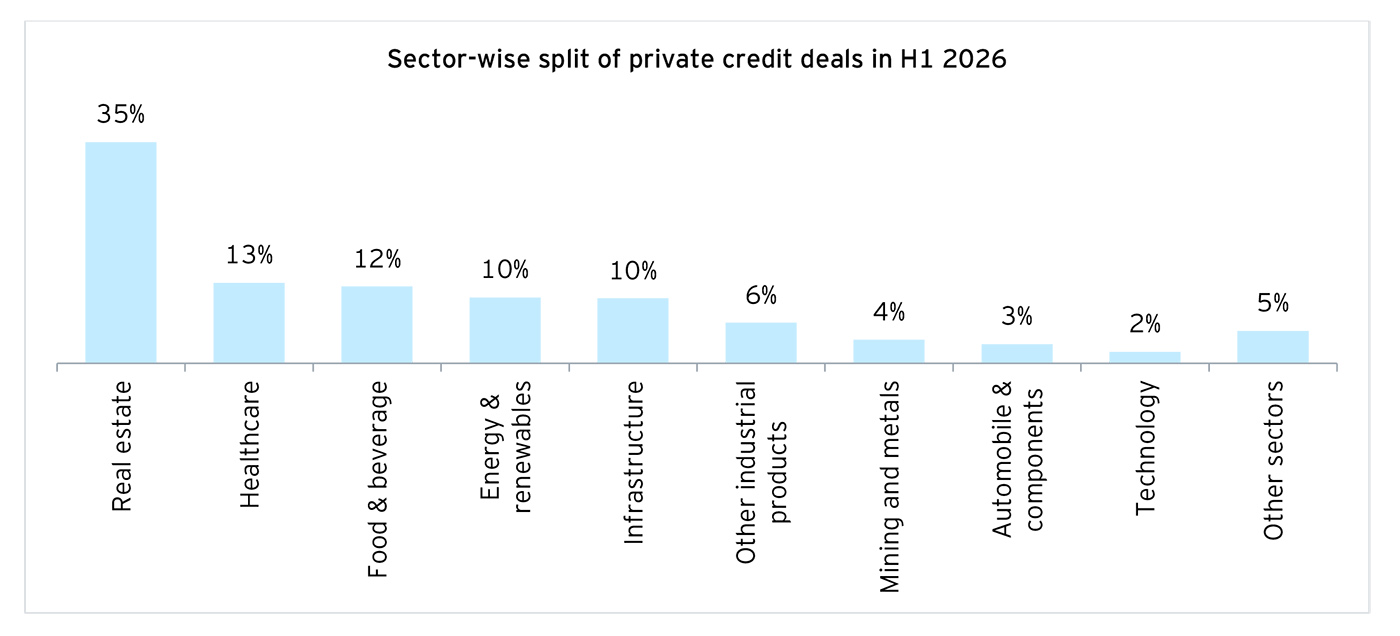
Named borrowers illustrate the spread. Kalpataru’s real estate arm raised $176 million for refinancing, HyFun Foods $156 million, and Inspira Group’s Lenexis Foodworks $113 million in acquisition funding, while GMR Group secured $150 million and Manipal Group $124 million. Refinancing dominated deal rationales, alongside real estate project funding, HoldCo funding, and acquisition financing.
Regulatory tailwind
The half also brought reform. The IBC Amendment Act, 2026, in force since 26 May, is intended to speed up the admission of insolvency cases, strengthen creditor rights, and improve oversight of liquidation, while codifying the clean-slate principle that shields buyers of distressed assets from legacy claims.
The liberalisation of the external commercial borrowings regime, meanwhile, opens offshore capital to acquisitions that result in control of a target company – widening the funding routes for M&A alongside domestic banks and private credit funds.